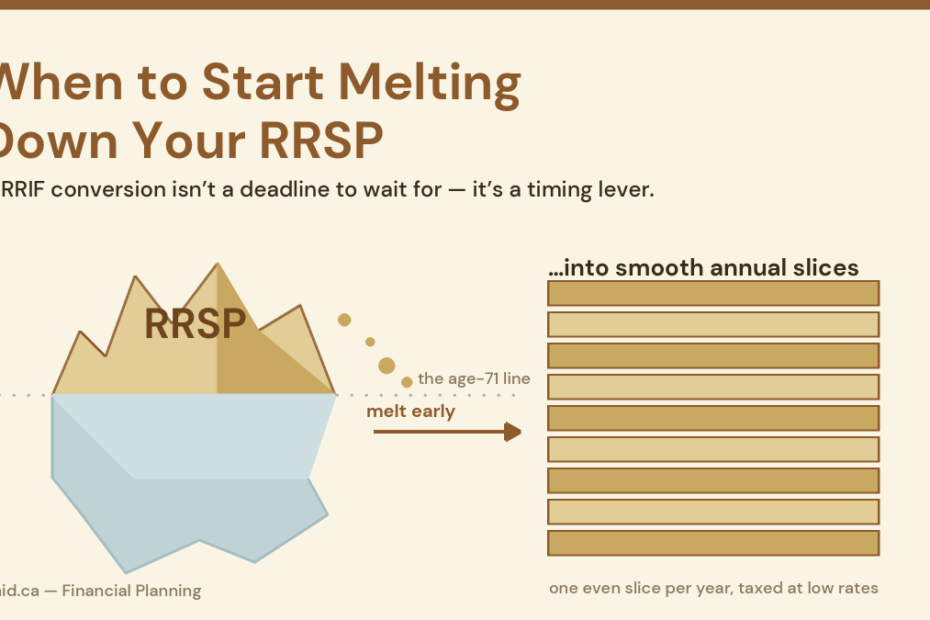
When to Start Melting Down Your RRSP
Most owners I sit with treat their RRSP like a dam they are not allowed to touch until the government opens the gates at 71.…
Most owners I sit with treat their RRSP like a dam they are not allowed to touch until the government opens the gates at 71.…
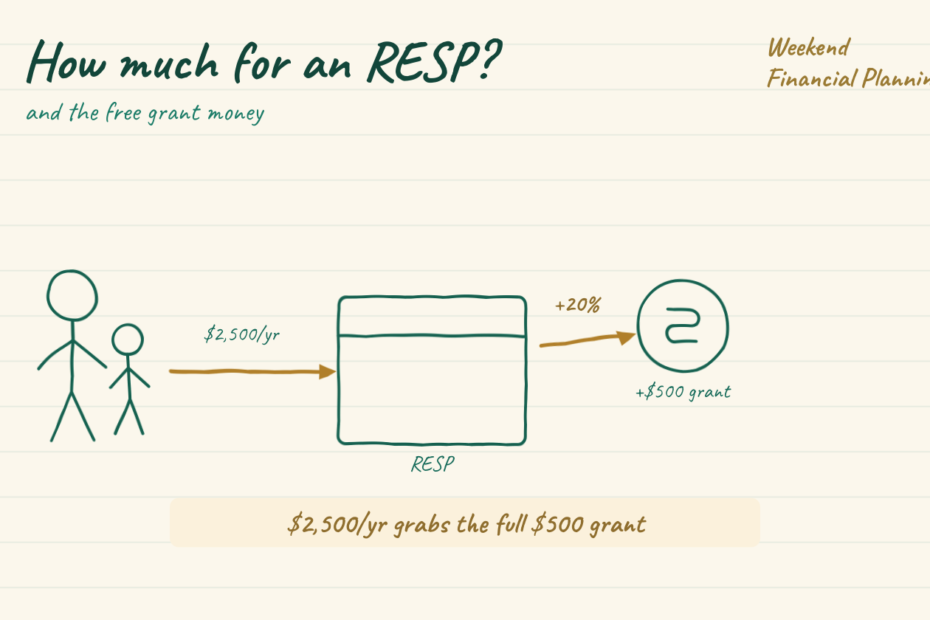
How much should you save in an RESP? About $2,500 a year captures the full 20% CESG grant: $500 a year, up to $7,200 per child. Start early and let it compound.
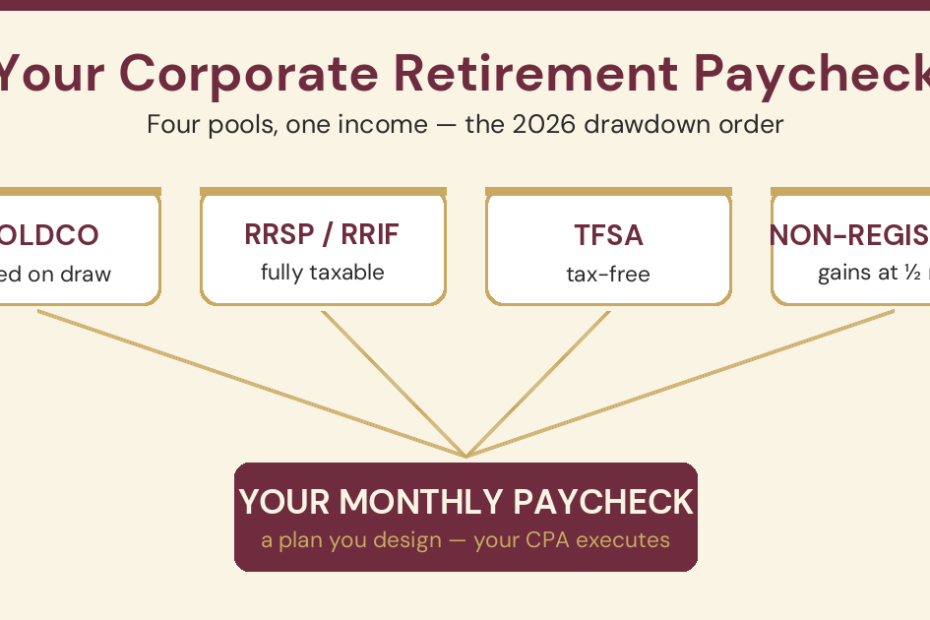
A financial planner's framework for turning your holdco, RRSP and TFSA into a tax-smart retirement paycheck in 2026 — what to draw first, in what order, and why.
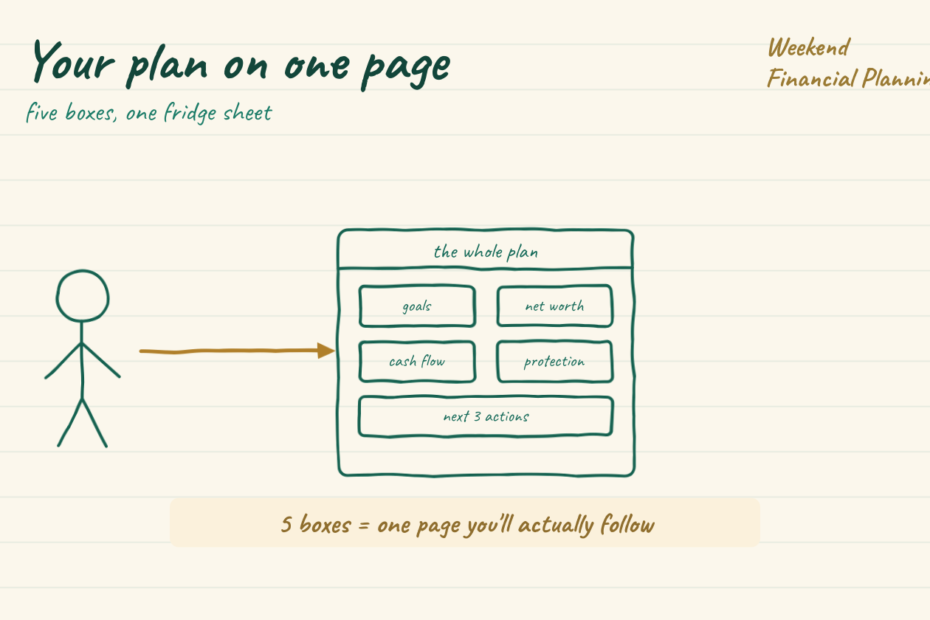
A one-page financial plan puts five things on a single page you will actually follow: goals, net worth, cash flow, protection, and your next three actions.

The five-instrument map for Muslim Canadian households in 2026: the will, beneficiary designations, incapacity documents, life insurance, and the corporate layer — where faraid interacts, where Canadian law overrides, and whose lane each piece sits in. A planner’s framework — not legal, tax, or Shariah advice.

Sinking funds turn predictable non-monthly bills into a monthly number: take each annual cost, divide by 12, and auto-save it into named funds so the bill is covered.

The corporate hub for Muslim business owners in 2026: where the surplus sits, the four tax mechanics that move the math (AII grind, RDTOH, CDA, foreign withholding), what a CCPC halal portfolio can actually hold, and how the corporate layer exits. A planner’s framework — not product, tax, or Shariah advice.

Couples and money: combined, separate, or hybrid? For unequal incomes, fund a joint account in proportion to income, plus personal accounts you each control.

Musharaka, ijara, murabaha — and the Manzil, EQRAZ, Canadian Halal Financial, and Servus Halal landscape as it stands in 2026. A planner’s framework for the halal home-financing decision: three buyer personas, the FHSA + HBP integration, and what the structure premium actually costs. Not a product pick.

TFSA or RRSP first? Choose by tax rate: RRSP if you are taxed higher now than in retirement, TFSA if your rate is low or similar or you want flexibility.