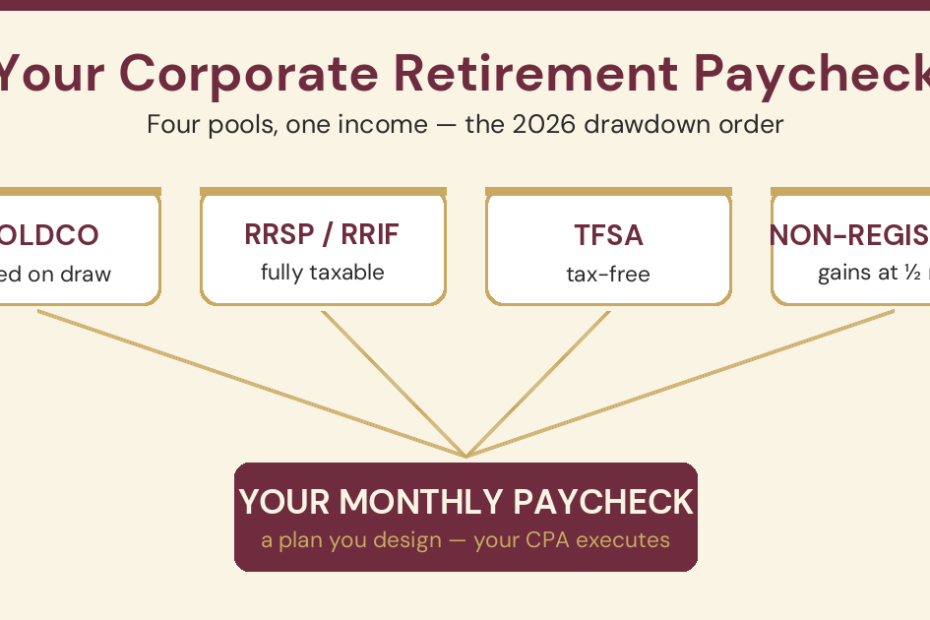
Turning Your Corporation Into a Retirement Paycheck — The 2026 Decumulation Plan
A financial planner's framework for turning your holdco, RRSP and TFSA into a tax-smart retirement paycheck in 2026 — what to draw first, in what order, and why.
A financial planner's framework for turning your holdco, RRSP and TFSA into a tax-smart retirement paycheck in 2026 — what to draw first, in what order, and why.

The five-instrument map for Muslim Canadian households in 2026: the will, beneficiary designations, incapacity documents, life insurance, and the corporate layer — where faraid interacts, where Canadian law overrides, and whose lane each piece sits in. A planner’s framework — not legal, tax, or Shariah advice.

Do you need a will? If you own property, have a partner, kids, or a business, yes, now. Without one your province decides who inherits and who raises your kids.

Beneficiary designations override your will. Whoever is named on your RRSP, TFSA, or life insurance gets it, so name a primary and a contingent.

How much life insurance do you need? Size it to your debts plus your income times the years your family depends on it, minus what you already have.